Saturday, June 5, 2010

Capital budgeting-Special decision situation

  • Adjusted NPV
  • Modified NPV and modified IRR
  • Equity NPV/IRR & Project NPV/IRR
  • Inflation under capital budgeting
  • Comparison in case of unequal lives/Equivalent annual NPV
  • Replacement decision

Adjusted NPV

Two-step NPV:

Step 1: 100%-equity finances, no issuing cost, asset b. Focus is on the inherent economic value of the project

Step 2: financing aspects of the project: issuing costs, capital grants or interest subsidies

APV= base case NPV – flotation cost +tax advantage of debt.

Where base case NPV= NPV of the project assuming that it is all equity financed.

Flotation case = cost incur to raise the money

Tax advantage of debt = PV of ITS discounted at interest rate on debt.

Technically, an APV valuation model looks pretty much the same as a standard DCF model. However, instead of WACC, cash flows would be discounted at the unlevered cost of equity, and tax shields at the cost of debt. APV and the standard DCF approaches should give the identical result if the capital structure remains stable.

lightbulbA project involve initial investment Rs 1,00,000 to be financed equally by equity and 10% debt. The whole of the initial investment shall be in fixed assets. Straight line depreciation is allowed for tax purpose assuming 5- year working life and no terminal value. Project EBDIT are as below:

Year

1 2 3 4 5

EBDIT (Rs ’000)

40 45 45 40 35

Cost of an unlevered equity is 15% and tax rate is 40%. The loan is repaid in 5 equal annual installments. Determine APV for the project.


Modified NPV and modified IRR

The NPV method assumes that cash flows are reinvested at the firm’s discount rate while the IRR method assumes that cash flows are reinvested at the project’s IRR. However, it may be that neither of these assumptions are correct.

Modified NPV as follows:

  • Compute the cash flow and cash outflow as usual
  • Compute PV cash outgo by using cost of capital as discount rate
  • Find the future cash flows at the given rate of investment for the remaining years. So if the project is for the 5 years, the cash flow generated in first year end shall be compounded for remaining 4 years. Similarly the cash inflow generated in second year end shall be compounded for 3 years and so on.
  • Take the total of future cash values which may be termed as future value or terminal value.
  • Find the PV of the cash inflow In the following manner: image
  • Modified NPV: PV of cash inflows- PV of cash outgoes

Modified IRR:

The cost of capital or discount rate at which modified NPV is Zero is know as Modified IRR.

lightbulbYou are trying to choose between the following projects, but the correct reinvestment rate for your company is 15%, whereas the firm’s discount rate is 12%. Calculate each project’s NPV, IRR, modified NPV and modified IRR and select the better project.

Year Project A Project B
0 -10,000 -10,000
1 8,000 1,000
2 4,000 4,000
3 1,000 10,000

Equity NPV/IRR & Project NPV/IRR

NPV or IRR from the point of view of equity shareholder is called Equity NPV or Equity & similarly NPV or IRR computed from the point of view of overall company or project is called project NPV or project IRR.

image

lightbulbXYZ Ltd., an infrastructure company is evaluating a proposal to build, operate and transfer a section of 35 kms. of road at a project cost of Rs. 200 crores to be financed as follows:

Equity Shares Capital Rs. 50 crores, loans at the rate of interest of 15% p.a. from financial institutions Rs. 150 crores. The Project after completion will be opened to traffic and a toll will be collected for a period of 15 years from the vehicles using the road. The company is also required to maintain the road during the above 15 years and after the completion of that period, it will be handed over to the Highway authorities at zero value. It is estimated that the toll revenue will be Rs. 50 crores per annum and the annual toll collection expenses including maintenance of the roads will amount to 5% of the project cost. The company considers to write off the total cost of the project in 15 years on a straight line basis. For Corporate Income-tax purposes the company is allowed to take depreciation @ 10% on WDV basis. The financial institutions are agreeable for the repayment of the loan in 15 equal annual installments – consisting of principal and interest.

Calculate Project IRR and Equity IRR. Ignore Corporate taxation.

Inflation and Capital Budgeting

 Inflation erodes the purchasing power, money and hence investors requires compensation for inflation. Since a project generates CF over a no. of Years the inflation effects may be dominant. Hence inflation is an important component in Capital budgeting. The principal of inflation and Capital Budgeting states that nominal/real CFs should be discounted at nominal/real Kc. In case of inconsistency we can adjust either the CFs or Kc. However sometimes inflation rates for revenue and cost are separately given. In such a a case we can only adjust CFs and not Kc.

  • Money cash flow=Real cash flow*(1+ inflation rate)
  • (1+money dis rate)= (1+ real dis rate)*(1+inflation rate)

Inflation rate may be symmetrical( one rate) or asymmetrical (multiple rate). Symmetrical inflation means all items of revenue and cost have undergone same level of inflation. Asymmetrical inflation means some items have suffered inflation at the rate that are different from those of others.

lightbulb D Limited, has under review a project involving the outlay of Rs. 55,00 and expected to yield the following net cash savings in current terms :

Year 1 2 3 4
Rs 10,000 20,000 30,000 5,000

The company’s cost of capital, incorporating a requirement for growth in dividends to keep pace with cost inflation is 20%, and this is used for the purpose of investment appraisal. On the above basis the divisional manager involved has recommended rejection of the proposal. Having regard to your on forecast that the rate of inflation is likely to be 15% in year 1 and 10%, in each of the following years, you are asked to comment fully on his recommendation. (Discounting figures at 20% are 0.833, 0.694, 0.579 and 0.482 respectively for year 1 to year 4.) (ICWAI)

Comparison in case of unequal lives/ Equivalent annual NPV

In case of life disparity we use annual capital charge (ACC) or equivalent annual net present value concept for each project by applying the following formula

image

Company X is forced to choose between two machines A and B. The two machines are designed differently, but have identical capacity and do exactly the same job. Machine A costs Rs. 1,50,000 and will last for 3 years. It costs Rs. 40,000 per year to run. Machine B is an ‘economy’ model costing only Rs. 1,00,000, but will last only for 2 years, and costs Rs. 60,000 per year to run. These are real cash flows. The costs are forecasted in rupees of constant purchasing power. Ignore tax. Opportunity cost of capital is 10 per cent. Which machine company X should buy?

Replacement decision

Initial investment = cost of new machine – PT salvage value of old machine.

Operating flow = EBDIT (1-t) +DTS

EBDIT savings in operating cost and DTS = DTS on new machine – DTS on old machine.

Terminal flow = PTSV from new machine- PTSV from old machine.

lightbulbS Engineering Company is considering to replace or repair a particular machine, which has just broken down. Last year this machine costed Rs. 20,000 to run and maintain. These costs have been increasing in real terms in recent years with the age of the machine. A further useful life of 5 years is expected, if immediate repairs of Rs. 19,000 are carried out. If the machine is not repaired it can be sold immediately to realize about Rs. 5,000 (Ignore loss/gain on such disposal).

Alternatively, the company can buy a new machine for Rs. 49,000 with an expected life of 10 years with no salvage value after providing depreciation on straight line basis. In this case, running and maintenance costs will reduce to Rs. 14,000 each year and are not expected to increase much in real term for a few years at least. S Engineering Company regard a normal return of 10% p.a. after tax as a minimum requirement on any new investment. Considering capital budgeting techniques, which alternative will you choose? Take corporate tax rate of 50% and assume that depreciation on straight line basis will be accepted for tax purposes also.

Given cumulative present value of Re. 1 p.a. at 10% for 5 years Rs. 3.791, 10 years Rs. 6.145.

Friday, June 4, 2010

Capital budgeting-Techniques of evaluations

Introduction:

Capital budgeting decision are considered to be extremely important of strategic impact, huge amounts involved and irreversibility

A project may be defined as a huge outflow of fund followed by a stream of future inflow.

Steps in capital budgeting

Generation of cash flow

Estimation of discount rate

Selection criteria

Cash flow or accounting profits

Demerits of accounting profit for capital budgeting problems

Affected by non cash items like depreciation

Ignores time value of money

Manipulative

Techniques of Evaluation

image

Accounting rate of return (ARR)

image or


image

Accept/Reject: higher the better

lightbulb A project involves a capital outlay of Rs 1,00,000. PBDIT for 5 years is expected to be Rs 25,000, Rs 30,000 Rs 40,000 Rs 45,000 & Rs 48,000. Corp[orate tax rate is 50% and depreciation on WDV basis is 40%. Find the AROR of the project. (Assume that the entire profit is withdrawn)

Earnings Per Share (EPS)

EPS is one of the major criterion for capital investment appraisal. The value of a firm is maximised if the market price of equity shares are maximised.

Net present value (NPV)

NPV= PV of inflows-PV of outflows

image

Important points to consider:

Cash outgo

Cash inflow

Discounting rate

Tax rate

Depreciation

Scrap

Carry forward & set off of losses

Subsidy

Use of probabilities

Overhead allocation

Release of working capital

Earnings

Accept/Reject:

NPV>0: Accept

NPV=0: Indifferent

NPV<0: Reject

lightbulb Ltd. has two projects under considereation A & B, each costing Rs. 60 lacs.
The projects are mutually exclusive. Life for project A is 4 years & project B is 3 years. Salvage
value NIL for both the projects. Tax Rate 33.99%. Cost of Capital is 15%

Internal rate of return (IRR)

Allows the risk associated with an investment project to be assessed

The IRR is the rate of interest (or discount rate) that makes the net present value = to zero

Accept/Reject:

IRR>cost of capital: Accept

IRR=cost of capital : Indifferent

IRR<cost of capital : Reject

smile_nerdConflict between NPV and IRR:
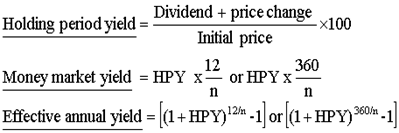
For a single project NPV and IRR will give the same accept or reject decision i.e. conflict does not exist.

For two mutually exclusive projects there may be conflict between NPV and IRR.

Cause of conflict- the conflict between NPV and IRR arises mainly on account of the difference in reinvestment assumption. NPV assume reinvestment rate of the intermediate cash flows to be Kc while IRR assume reinvestment to be IRR itself.

Situation in which conflict occurs

Size disparity

Cash flow timing disparity

Profitability index (PI)

imageAllows a comparison of the costs and benefits of different projects to be assessed and thus allow decision making to be carried out

Accept/Reject:

PI>1: Accept

PI=1: Indifferent

PI<1: Reject

lightbulb  S Ltd. has Rs. 10,00,000 allocated for capital budgeting purposes. The following proposals and associated profitability indexes have been determined:

Project

Amount (Rs.)

Profitability Index

1 3,00,000 1.22
2 1,50,000 0.95
3 3,50,000 1.20
4 4,50,000 1.18
5 2,00,000 1.20
6 4,00,000 1.05

Which of the above investments should be undertaken? Assume that projects are indivisible and there is no alternative use of the money allocated for capital budgeting. ) (November 1998)

Pay back period/pay off period/capital recovery period

image

The length of time taken to repay the initial capital cost

Accept/Reject:

Project with lower pay back period is preferred

smile_nerdOne of the limitation of the PBP is that no rate of return can be disclosed. If ROR is required to be computed in the PB situations, compute PB reciprocal as below, which is submitted as ROR:

image

Discounted pay back period

In Traditional Payback period, the time value of money is not considered. Under discounted payback period, the expected future cash flows are discounted by applying the appropriate rate, i.e., the cost of capital.

Summary

Particulars

NPV IRR BCR Dis PB

Interpretation

It is net addition to the wealth of ESH

It is the rate of return on unrecovered Inv bal.

It is the profitability per unit of funds invested

It is the no. of yrs in which the project pay back the amt invested in it considering TV

Discount rate

Ke, Kc,K NA Ke, Kc,K Ke, Kc,K

Hurdle/cut off

0 Discount rate 1 subjective

Absolute/relative

Absolute Relative Relative NA

Valuation of Securities

Bonds

Fixed coupon Bond

The intrinsic value of a bond in the present value of the future coupon and redemption amount discounted at the required rate of return. If he market price is lower/higher, the bond is under/over priced & should be purchased & short sold.

lightbulb A bond will be redeemed equally at the end of 4th & 5th year at a premium of 10%.

Risk free real rate = 5% p.a.

Expected inflation = 4%

Risk premium = 6%

Current market price =Rs 4,950

Find out the intrinsic value and advice the investor

Bond yields:

Traders in the bond mkt generally compares bonds in terms of yield rather than IV, There are three measure of yield

  • Coupon Rate (CR): The annual interest rate on a bond.
  • Current yield (CY): It is also not representative as it ignore the CF beyond the current period
  • Yield to maturity (YTM): it is the IRR of the bond

Relationship of the above measure of yield:

For bonds trading at par: YTM=CY=CR

For bond trading at discount: YTM>CY>CR

For bond trading at Premium: YTM<CY<CR

From a computational perspective, YTM is given by outflow=inflow

However, in case of plain vanilla bond (i.e. bond with constant coupon & 1 shot i.e. bullet redemption) YTM is allowed to be computed by a shortcut approximate formulae given by :

image

lightbulb: Find out the YTM of a 10% Rs 5000 FV bonds, maturity 5 years & presently trading at 4720. If the ROR is 13%p.a. should the bond be purchased

Case 1: If income tax rate is 30% and capital gains tax is 10%. Find out the post tax YTM of the bond

Case 2: Ignore taxation and recomputed the YTM of the bond given that the bond would be redeemed in 2 equal installments At the end of 4th & 5th year.

Case 3: Now consider semi annual coupon payment and one shot redemption. Find the Annualized current yield & YTM.

PRICE YIELD relationship

There is negative relationship between bond price & interest rate, Thus if yield rises/falls, bond price is expected to fall/rise. However price yield relationship is not linear. Instead it is convex to the origin as shown : image

Thus the % increase in bonds prices from given decrease in YTM is higher than % decrease in bond price than the same increase in YTM. This favourable property is positive convexity

In order to quantify bond volatility i.e. sensitivity of bond w.r.t interest rate, we draw a tangent to the price yield curve. The slope of the tangent is the measure of volatility. image

Bond volatility (depends on maturity) i.e. the slope of the tangent is known as Modified duration (MD). Thus if MD is 6.2%, it means that for a 1% change in interest rate bond price is expected to change by 6.2% in the opposite direction ignoring convexity


Computation of bond volatility:

image 

Duration is the average holding period where all CF from the bond are deemed to have received one shot

So duration= ∑wx/ ∑w; where ‘x’ refers to periods of CFs received ‘w’ is the PV of the cash flow discounted

lightbulb Consider a 14% , Rs1000 (FV), 5yr bond presently trading at Rs942. compute bond volatility & expected intrinsic price, if interest rate were to fall by 60 basis point

Bond portfolio management:

Passive

Active

Believe that the market are efficient i.e. all security are correctly priced

Believe that the market are inefficient & there are pocket of mispricing

Invest in a diversified portfolio to replicate a benchmark index

Invest in a non-diversified portfolio of bonds which are supposedly underpriced

Does not engage in interest rate anticipation

Use interest rate anticipation strategies

Low portfolio churning leading to lower transaction cost

Low portfolio churning leading to lower transaction cost

Interest rate anticipation strategies:

This strategies involve change in portfolio duration (DP) in anticipation of a change in interest rate.

DP is the weighted average of the bonds comprising the portfolio. The strategies are:

If interest rates are expected to fall, bond prices are expected to rise. Since higher duration bonds are more volatile than lower duration bonds, the fund manager should increase DP by shifting funds from lower duration bonds to higher duration bonds

If interest rates are expected to rise, bond prices are expected to fall. Since higher duration bonds are more volatile than lower duration bonds, the fund manager should decrease DP by shifting funds from higher duration bonds to lower duration bonds

IMMUNISATION:

Interest rate risk refers to the risk of not realizing the promised YTM due to changes in interest rate:

Interest rate risk has two components

Re investment risk= compounding exercise

Price risk discounting exercise

YTM is based on two unrealistic assumptions

The intermediate CF are assumed to have been reinvested at YTM yield

The bond is assumed to be held till maturity

The first assumption of the YTM seems to kill reinvestment risk & the second assumption kills the price risks. However, in rectify interest rate keep on changing & the investor have to suffer both the risk

Since reinvestment risk & price risks are acting in opposite direction, they tend to cancel out each other at a particular point of time i.e. Macaulay's Duration (D). Duration may now been defined as that holding period where re investment effect & price effect cancel out each other such that the investor is immunized from changes in interest rates. An investor should always buy a bond or a portfolio of bonds whose duration is equal to his investment horizon

Floating rate bond:

This bond doesn’t have a fixed coupon rate, instead there would be a coupon formulae which relates the coupon rate with some market reference rate such as prime lending rate (PLR), London inter bank rate (LIBOR), MIBOR etc

The investor/issuer of a floating rate bond expects interest rate to rise or fall. In order to protect themselves against adverse fluctuation in interest rate, a floating rate bond would generally be accompanied with a cap and a floor features. A combination of cap & floor is know as collar

lightbulb Consider a 5 yr, Rs 1000 FV floating rate bond a coupon of 200 B.P over PLR. Presently PLR is 9%. A forecast of PLR is likely to prevail at the beginning of each of year for next 4 years is shown below:

YIELD CURVE STRATEGIES:

Yield curve is a graphical representation of the term structure of interest rates. The term structure of interest rates is a relationship between YTM & maturity , other factors remaining constant between

The yield curve can have any shape. The popular shapes of the yield curves & their interpretations are as follows

Upward sloping yield curve: Interest rate are expected to rise. So the investor should choose a short term bond

Downward sloping yield curve: Interest rate are expected to fall. So the investor should choose a long term bond

Flat yield curve: Interest rate are not expected to change. So the investor should choose bond with highest YTM irrespective of maturity long term bond

Spot rate & forward rates:

Spot interest rate is the interest rate applicable for borrowing/investment today and is denoted by ron. On the other hand forward interest rate is the interest rate applicable for borrowing/investment to take place later on & denoted by ft1t2(i.e. interest rate applicable for borrowing/investment after t1 yrs for t2-t1 yrs

To prevent arbitrage, a certain relationship must hold good between spot interest rate & forward interest rate

Therefore, (1+ro2)2= (1+ro1)(1+f12)

Ro2=[(1+ro1)(1+f12)]1/2-1

Bond valuation:

Value of equal interest bond image

Value of Zero coupon bond image

Value of perpetual bond    image

Value of Semi-annual interest bond

Value of floating rate bond

Bond with changing yield rates

Value of optionally convertible debenture/bonds

Equity valuation:

Equity valuation is highly subjective and judgmental exercise recording and analysis of the economy industry and company. There are several methods which may be classified as follows:

  • Relative: based on the price multiple
  • absolute : dividend discount model (minority perspective ) & free cash flow approach (control perspective)
  • residual : using the concept of EVA

Dividend discount model :

Intrinsic value of this year is the TV of the expected future dividends discounted at the client rate of return

IV= D1/(1+Re)+D2/(1+Re)2+……+

so there are two inputs in the valuation process .

Equity capitalization rate

Forecast of futures dividend

As per CAPM Investors holds diversified portfolios and he requires compensation for bearing only systematic risks captured by B . B refers to the sensitivity of stock’s return to the mkt returns. Thus if a 10% change in market returns brings about 15% change in the stock’s return, then B is 1.5

Required rate of per CAPM: Rf+ B( Rm- Rf)

There are three methods of dividend forecast

No Growth

Constant growth

Multiple growth

Method I: g can be taken as average of the past after suitably adjusting for any bonus issue or share split. The averaging may be done using simple average or compound average

Method II: Sustainable growth rate is often deemed as the growth that a firm can achieve using only internal funds. Thus g= retention ratio ROE

Methods III: Multiple growth DDM

Free Cash flow approach

An acquirer is not interested in the dividend policy of the target, instead he is concern with the CF generating ability of the target. Hence FCFA is preferred over DDM in case of Mergers and Acquisitions.

There are 2 types of free cash flow for the firm (FCFF) and free cash flow for the equity (FCFE) in general FCF refers CF net of investments.

FCFF Approach

Value of the firm is equal to PV of FCFF discounted at Ke. Thus value of equity is equal to value of the firm – market value of debt+ market value of non trade investments.

Residual Approach of Valuation

Residual income or EVA refers to post Tax earnings generated by firm over and above what is required by share holders , therefore EVA = PAT – (KE x net worth) or (ROE – KE ) x Net worth or NOPLAT – (KC x invested capital).

EVA is a source of value creation and is reflective of firm investing in positive NPV projects. We define market value added (MVA) as the present value of future EVA so value of firm equity net worth + MVA or value of the firm = invested capital + MVA.

Relative method of valuation

Relative valuation involves valuing a firm on the basis of how similar firms are valued. It requires the use of price multiples . Price to earning ratio, price to sales ratio, price to book value ratio. The challenges to relative valuation lies in computing the justified price multiples. This can be done by following method.

  1. Average of the industry
  2. Regression equation method
  3. Using DDM.

Thursday, June 3, 2010

Time value of money & basic concept

Interest rate

Interest rate may comprises of 3 components

  • Risk free real rate i.e. compensation for sacrifice current consumption
  • Inflation premium i.e. compensation for the loss of purchasing power
  • Risk premium i.e. compensation for bearing risk

Based on the these components, there are 4 types of interest rates:

  • Risk free real rate of return
  • Risk free nominal rate of return
  • Risk adjusted real rate of return
  • Risk adjusted nominal rate of return

Sum: Consider a project with the following cash flows:-

Year                          0               1                2             3

Cash Flow( in lacs)   -500          200            250          200

These cash flow include inflation of 3% p.a

Cost of capital 12%. Find NPV of the project

DCF

As per discounted cash flow techniques (DCF). The intrinsic value of an asset, is the present value of the future cash flow discounted at the required rate of return

There should be consistency between the nature of cash flow and discount rate

  • Nominal/real cash flow should be discounted at Nominal/real rate
  • Certain/uncertain cash flow should be discounted at risk free/risk adjusted rate


Different type of yield

image

 Bond equivalent yield (BEY): Since most bonds pay coupon semi annually there is a tendency in the market to compute BEY which is actual a special case of MMY with a base period of 6 months

image

Sum: An investor purchase a stock at Rs600. He sold the same at the end of 2 months for Rs625 and received a dividend of Rs 5, Find a) HPY , b) MMY C) EAY & D) BEY

Implied interest rate

Given a cash flow stream, the implied interest rate the one which equates outflow with the inflow standing at a particular time.

From a computational purpose:

  • If the CF span over at most 2 periods, we are suppose to exactly solve for the interest rate using linear or quadratic equation
  • If the CF span over more than 2 periods, we compute the interest rate approximately by the process of trial & error & the technique of linear interpolation or extrapolation

Sum: Consider a project with the following cash flows:-

Year                          0               1                2             3

Cash Flow( in lacs)   -500          200            250          200

Calculate IRR

Bond Valuation

The intrinsic value of a bond is the PV of the future coupon & redemption amount discounted at the required rate of return. If the market price is lower/higher than intrinsic values, then bond is underpriced/overpriced & should therefore be purchased/short sold respectively

Sum: Consider a two year Rs1000 face value 10% coupon rate bond which pays coupon semiannually. Find out the intrinsic value of the bond if the required rate of return is 14% p.a. compounded semiannually. Should the bond be purchased at the current price of Rs 965.

Annuity

An annuity is a series of equal periodical payments. If the payments are made at the end /beginning of each period, we call is an ordinary annuity/annuity due respectively

Sum:. X ltd is taking a machine on a 5 yrs lease. It has 2 options

Option1: Lease rentals Rs 10L payable at the end of each year

Option 2: Lease rentals Rs 9.5L payable at the beginning of each year

If the discount rate is 14%, find out the option the X ltd should choose.

Perpetuity

A perpetuity is annuity to continue for ever

image

If there is a cash flow stream which is expected to grow at a constant growth rate for ever its PV is given by

image


Equity valuation

As per the dividend discount model (DDM), intrinsic value of a share i.e.  the PV of expected future dividend discounted at the required rate of return

image

There are three patterns if dividend forecast

1) No growth DDM: This will be applicable for the firm having 100% payout ratio such DPS=EPS=perpetuity

2) Constant growth DDM: In this case, the firms dividend is expected to grow at a constant growth rate forever.

3) Multiple growth DDM: The firm will exhibit supernormal growth say for the first ‘n’ yrs beyond there would be perpetual normal growth rate.

Sum 1

X LTD has 100% payout ratio and is a no growth firm. It has an EPS of Rs 15 for the year just ended and the stock is presently trading at Rs. 132. If ROR is 14%  p.a. Find out the intrinsic value of the share and comment on its current price.

Sum 2

A firm recently paid a dividend of Rs 8 per share. This is expected to grow 6 p.a. for ever. Find out the value of the share if RoR is 14% p.a.

Sum 3

X ltd reported an EPS of Rs12 for the year just ended and a payout ratio of 40%. The earnings are expected to grow at 30% p.a. for the next 4 years. Beyond the 4th year, growth rate would be 6% forever. Find out the intrinsic value of the share if ROR is 18% p.a

Continuous compounding

Stock and bond prices changes on a real time basis given rise to the concept of continuous compounding. Obviously, if interest rate is ‘I p.a.’ compounded continuously, the interest factor i.e future value Rs 1 is more than (1+i)

Specifically the interest factor becomes ei

Sum: Consider a stock trading at Rs750. This stock has announced a dividend of Rs 25 payable 6 mts from now. If interest rate is 9% p.a. compounded continuously, find out the ex-dividend stock price. ( given e0.0225=1.0227)

Saturday, December 13, 2008

Financial services

NBFC

Meaning

Different categories of NBFC

legislation on NBFCs

Regulation of NBFCs

     Two compulsory prerequisites

      Computation of NOF

Procedure for obtaining registration

Processing of application by RBI

Cancellation of registration

Procedure for cancellation of registration

Appellate remedy

NBFCs exempted from registration

Lease

Meaning

Parties

Types

Salient features of Financial lease

Salient features of Operating lease

Hire purchase

Meaning

Condition

Modus operandi of HP system

Operating Lease & Financing lease

Basis Financing Operating
Life of contract    
Maintenance    
Cancellation    
Duration    
Risk of obsolescence    
cost of Assets    

HP & lease

Basis HP Lease
Ownership    
Down payment    
Depreciation    
Maintenance    
Capitalization    
Tax Benefit    
Risk of obsolescence    
Reporting    

HP & Installment Payment

Basis HP Installment
Ownership    
Call option    

Factoring

Types

  • Recourse and non-recourse factoring
  • Advance and maturity factoring
  • Disclosed and undisclosed factoring
  • domestic and export/cross border factoring

Function of factor

  • Maintenance/administration of sales ledger
  • collection of facility
  • financing trade debts
  • credit control and credit protection
  • Advisory services

Advantage of factoring

  • convertibility
  • definite pattern of cash inflows
  • Reduction in collection & administration costs
  • Compensating balance are not required

Factoring and forfaiting

Functions of merchant banker

Portfolio Management

Diversification

Systematic & unsystematic risk

CAPM

Functions of portfolio management

Objective of Portfolio management

Activities for an efficient management

Principal for effective management

Factors effecting investment decision in portfolio management

Fundamental analysis for identifying industries with growth potential

Portfolio theory

Traditional approach to portfolio management

Modern approach to portfolio management

Dow Jones theory to portfolio management

Formula plan

Fundamental analysis

Random walk theory to portfolio management

Technical analysis

Technical analysis Vs fundamental analysis

Use of matrix approach in investment decision

Types of risk involved with G-Sec

Qualified institutional buyers

Tuesday, December 9, 2008

Types of financing

Term Loan

  1. Duration
  2. Purpose of term loan
  3. Special features

Bridge finance/Loan

  1. Meaning
  2. Purpose
  3. Terms

Venture capital financing

  1. meaning
  2. methods
    1. Equity financing
    2. conditional loan
    3. income note
    4. participating debenture
  3. benefit
  4. limitation


Debt securitisation

  1. Meaning
  2. Process
  3. Steps involved in a securitisation process
  4. Parties involved in securitisation process
  5. instruments of securitisation
  6. benefit of originator
  7. Benefit to investors
  8. Recent scenarios

Promoters contribution is one of the principal means of financing the projects